Search Credit Card Offers
PREMIER Bankcard® Mastercard® Pre-Approved Offer Guide
A detailed guide to the PREMIER Bankcard® Mastercard® pre-approved offer, including the credit limit, fees, eligibility requirements, application process, credit reporting, and what to understand before responding.
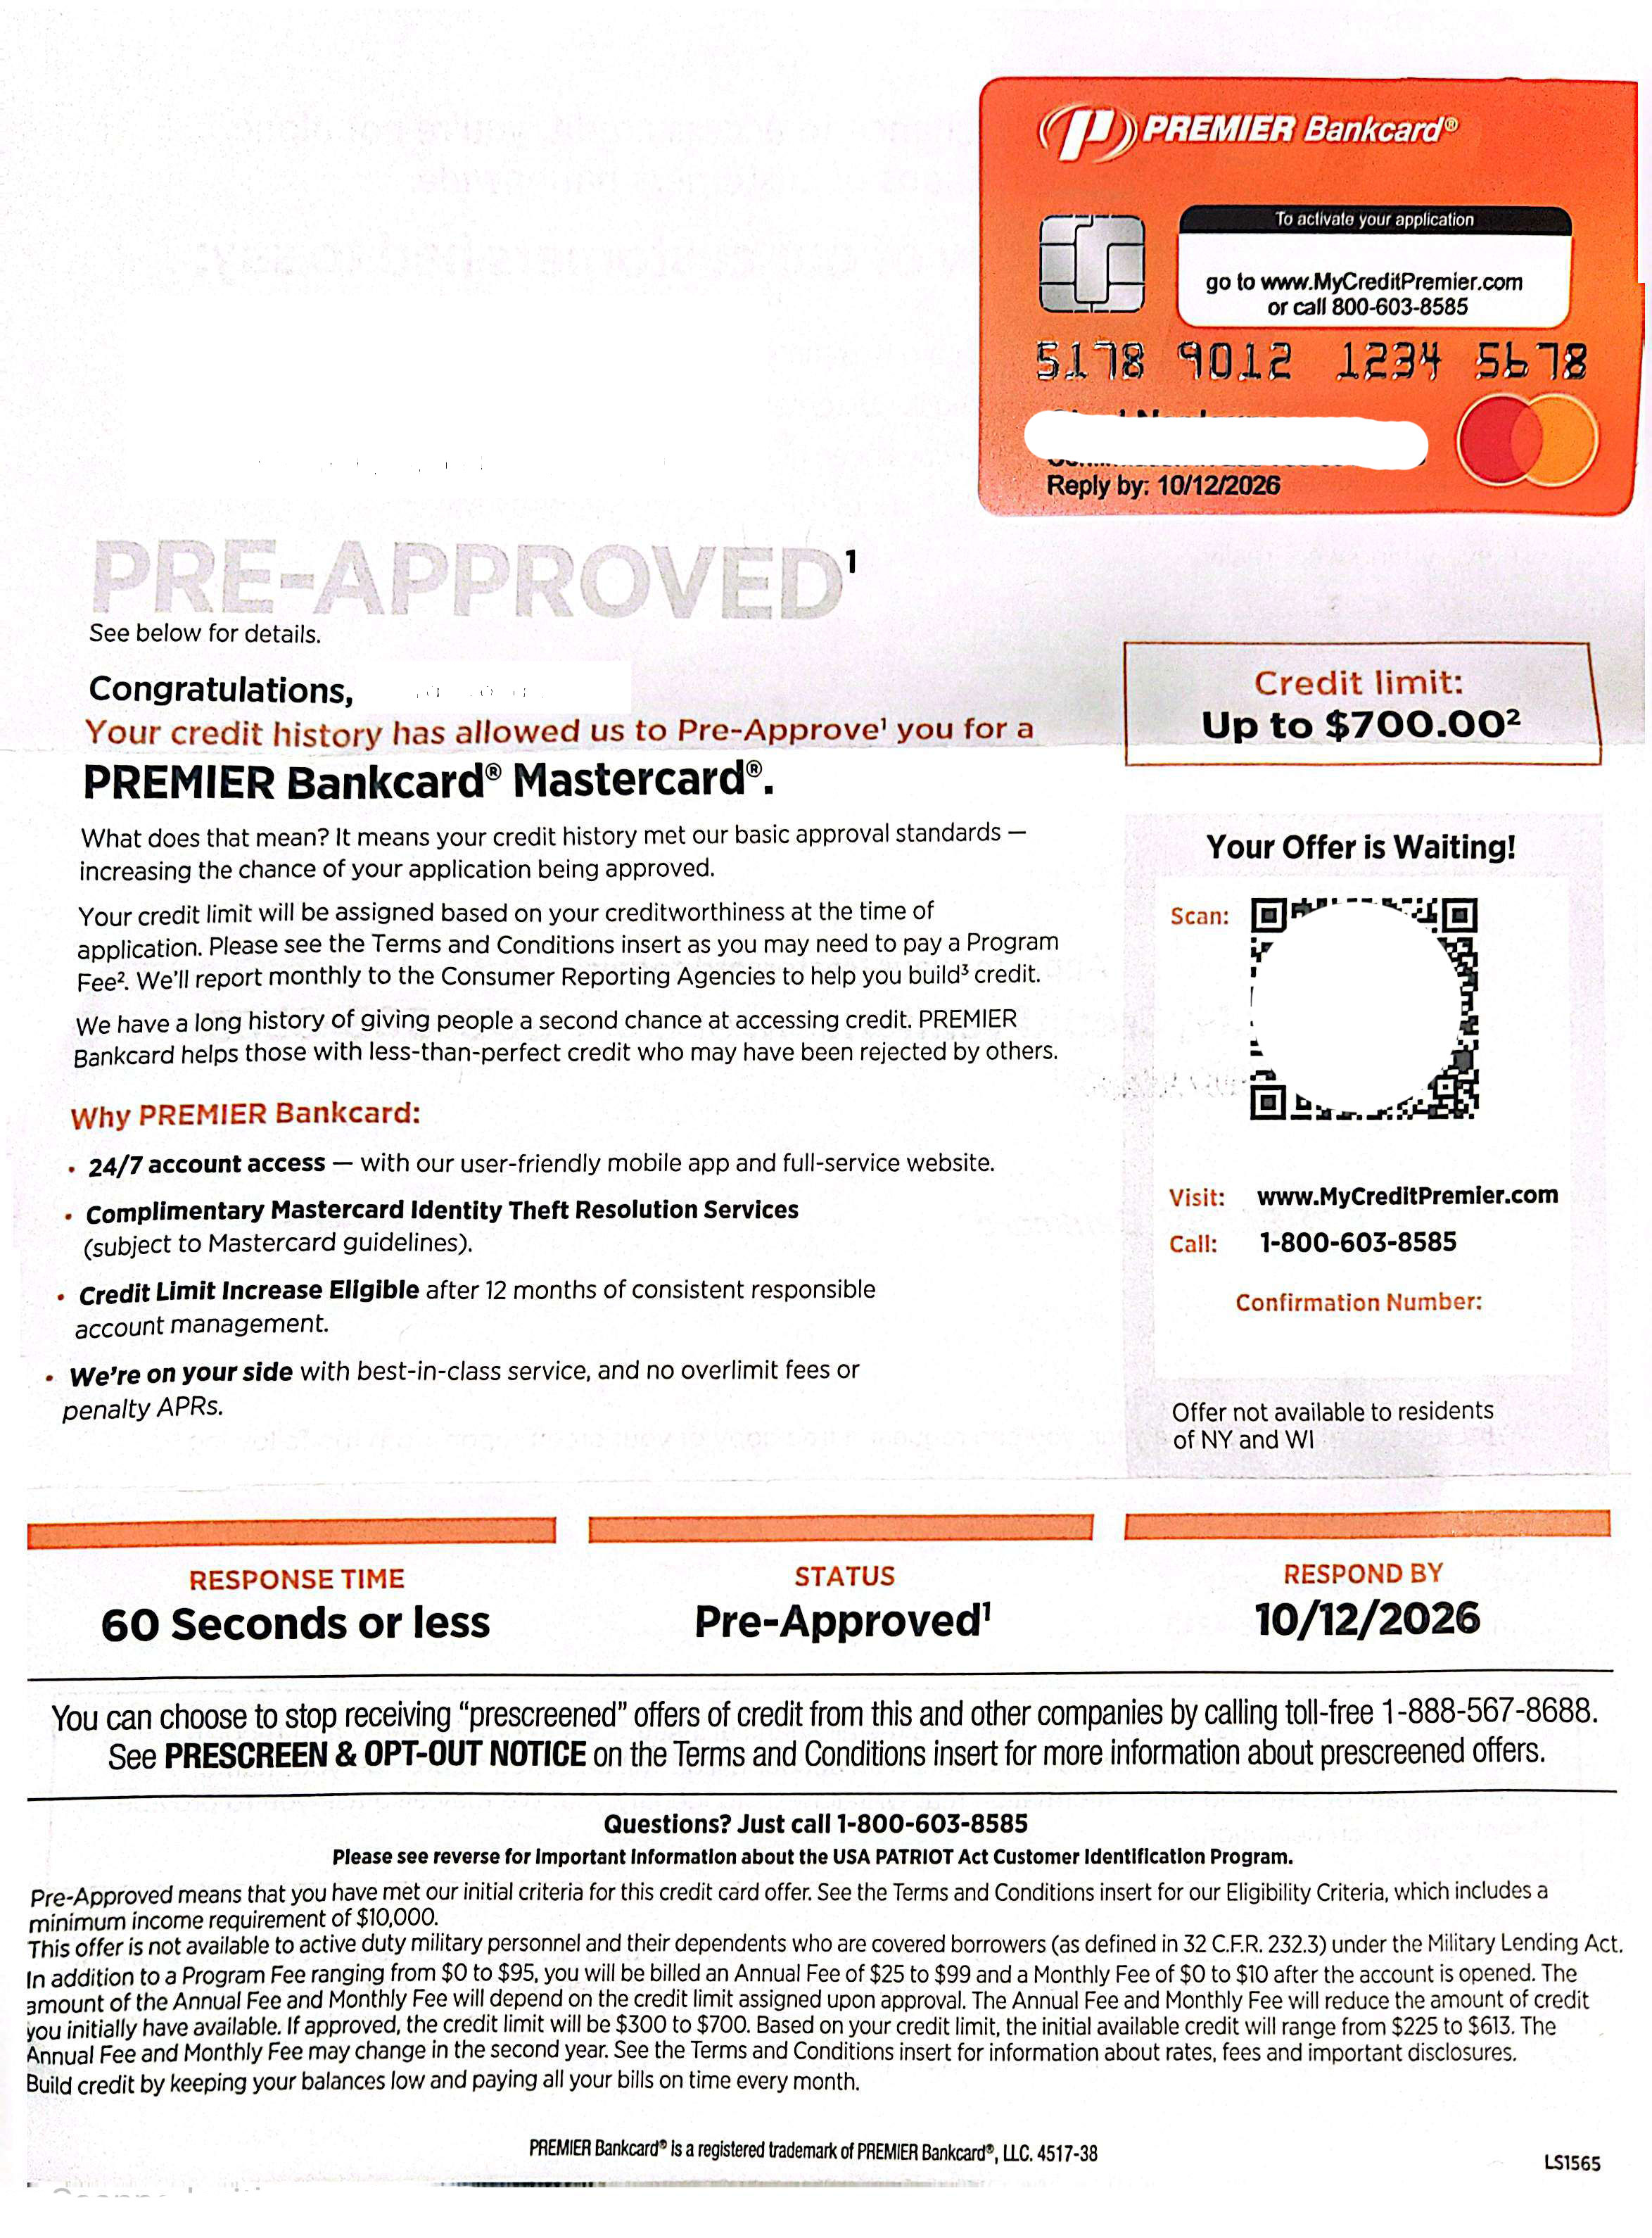
If you received a PREMIER Bankcard® Mastercard® pre-approved offer in the mail, there is quite a bit of information packed into the flyer and its accompanying disclosures. The large "PRE-APPROVED" message is only one part of the offer. The actual credit limit, Program Fee, annual fee, monthly fee, eligibility requirements, response deadline, and initial available credit are all important when deciding whether to respond.
The current offer discussed on this page states that the recipient's credit history met PREMIER's basic approval standards. It does not mean that an account has already been opened or that the advertised $700 maximum credit limit is guaranteed. The application still has to be completed, and the final credit limit is assigned based on creditworthiness at the time of application.
This guide breaks down the actual offer so you can separate the headline language from the details that affect the account.
Quick Offer Summary
| Card | PREMIER Bankcard® Mastercard® |
| Status on mailer | PRE-APPROVED |
| Credit limit if approved | $300 to $700 |
| Advertised maximum | Up to $700 |
| Initial available credit | $225 to $613 |
| Program Fee | $0 to $95 |
| Annual Fee | $25 to $99 |
| Monthly Fee | $0 to $10 |
| Minimum income requirement | $10,000 |
| Monthly reporting | Offer states that account information will be reported to Consumer Reporting Agencies |
| Credit Limit Increase language | Eligible after 12 months of consistent responsible account management |
| Response deadline | See Mailer for Deadline |
| Application website | www.MyCreditPremier.com |
| Application phone | 800-603-8585 |
Issuer: CreditSoup.com • Network: VisaSynced Daily Data Verified: Nov 2, 2026 | |
| |
Intro Rate: See website for Details*Intro (Purchases): See website for Details*Transfers: See website for Details*Intro (Balance Transfers): See website for Details*Intro APR Period: See website for Details*Purchase APR: See website for Details*Annual Fee: See website for Details*Credit Needed: Average/Fair/Limited/Poor/Good/Excellent | |
What Does "PRE-APPROVED" Actually Mean?
The most important distinction is that PRE-APPROVED does not mean the credit-card account is already approved and open. It means the consumer was selected through an initial prescreening process based on information available to the issuer or its credit-reporting partner.
The PREMIER mailer specifically states that your credit history met the company's basic approval standards. The same notice explains that the credit limit will be assigned based on creditworthiness at the time of application.
In other words, the mailer represents an invitation to apply based on an initial screening. You still have to respond, provide the required information, and complete the application process.
For a deeper explanation of the screening process, see How Credit Card Prescreening Works.
What PRE-APPROVED Does Not Mean
- It does not mean the account has already been opened.
- It does not guarantee the maximum $700 credit limit.
- It does not eliminate the application process.
- It does not mean the account has already started reporting to credit bureaus.
- It does not mean you are required to accept the offer.
Why Did You Receive This PREMIER Offer?
The flyer tells you the basic reason: PREMIER says your credit history met its initial criteria for this particular offer.
That does not necessarily mean you have a particular credit score, a particular amount of debt, or a specific credit history characteristic. The exact formula used to select recipients for this solicitation is not provided in the mailer.
It is therefore better to interpret the offer literally. Your available credit information matched criteria associated with the solicitation. The mailer is not a complete diagnosis of your credit profile.
For more on why a particular consumer may receive a prescreened offer, see Why You Received This PRE-APPROVED Offer.
How Do You Respond to the Offer?
The current mailer provides two primary ways to respond. You can visit www.MyCreditPremier.com or call 800-603-8585. The flyer also provides a QR code that can be scanned to reach the application process.
The mailer lists a response deadline of October 12, 2026. If you are reviewing an older or different version of the offer, use the response date printed on that particular mailer rather than assuming the date shown here applies.
The flyer also displays a confirmation number. Keep the original mailer available while responding because the offer information and confirmation details may be relevant to the application process.
For a more detailed walkthrough, see How to Respond to Your PRE-APPROVED Offer.
Response Information on the Current Flyer
- Website: www.MyCreditPremier.com
- Phone: 800-603-8585
- Response deadline: October 12, 2026
- Response time advertised: 60 seconds or less
- Status: PRE-APPROVED
How Much Credit Could You Receive?
The large number on the flyer is "Up to $700." That wording is important because $700 is the maximum advertised amount, not a guaranteed starting limit for every approved applicant.
The detailed disclosure provides the actual range: if approved, the credit limit will be between $300 and $700. The assigned amount depends on creditworthiness at the time of application.
| Offer Language | What It Means |
|---|---|
| Up to $700 | The advertised maximum credit limit |
| $300 to $700 | The disclosed range of credit limits if approved |
| Credit limit based on creditworthiness | The final assigned limit is determined when the application is evaluated |
This distinction is important when comparing the PREMIER offer with another credit card. Comparing another card's maximum advertised limit against PREMIER's $700 maximum does not necessarily tell you which starting limit you would actually receive.
For more detail, see Understanding Your PRE-APPROVED Credit Limit.
Why Is My Initial Available Credit Lower Than My Credit Limit?
This is one of the most important details in the flyer and one that is easy to miss.
The offer states that the approved credit limit will be between $300 and $700, while initial available credit will range from $225 to $613. The difference exists because applicable fees reduce the amount of credit initially available.
The flyer specifically states that the Annual Fee and Monthly Fee will reduce the amount of credit initially available. The exact relationship depends on the credit limit and fee combination assigned to the account.
| Item | Range in Current Offer |
|---|---|
| Credit limit | $300 to $700 |
| Initial available credit | $225 to $613 |
| Program Fee | $0 to $95 |
| Annual Fee | $25 to $99 |
| Monthly Fee | $0 to $10 |
This is why it is important to distinguish credit limit from available credit. The credit limit is the account's assigned maximum. Available credit is the amount you can actually use at a particular point in time after accounting for applicable charges and account activity.
What Fees Are Included in the Offer?
The current flyer provides considerably more fee information than the headline offer card. It states that a Program Fee ranging from $0 to $95 may apply. After the account is opened, the card carries an Annual Fee ranging from $25 to $99 and a Monthly Fee ranging from $0 to $10.
| Fee | Current Offer Range | Important Detail |
|---|---|---|
| Program Fee | $0 to $95 | May apply depending on the offer and approval terms |
| Annual Fee | $25 to $99 | Amount depends on the credit limit assigned upon approval |
| Monthly Fee | $0 to $10 | Amount depends on the credit limit assigned upon approval |
The Annual Fee and Monthly Fee may change in the second year. The mailer directs applicants to the Terms and Conditions insert for the applicable rates, fees, and important disclosures.
For a complete discussion of the current fee structure, see PREMIER Bankcard® Fees and Costs Explained.
Important: The fee ranges shown here come from the specific offer described on this page. Always review the Terms and Conditions included with your own mailer before applying because a different offer may contain different terms.
What Is the Minimum Income Requirement?
The eligibility information included with the current offer states a minimum income requirement of $10,000.
This requirement is separate from the prescreening statement. Being selected for the mail offer does not eliminate the eligibility criteria that apply when the application is submitted.
The flyer also identifies additional eligibility restrictions. The current offer is not available to residents of New York or Wisconsin, and it states that the offer is not available to active duty military personnel and their dependents who are covered borrowers under the Military Lending Act.
The Terms and Conditions supplied with the offer should be reviewed for the complete eligibility criteria.
Does PREMIER Report the Account to Credit Bureaus?
Yes, the current mailer states that PREMIER will report monthly to the Consumer Reporting Agencies. This is one of the central features highlighted in the offer because reported account activity can become part of your credit history after the account is opened.
However, reporting an account does not guarantee that your credit score will increase. The effect of account information depends on what is reported and how the information fits into your overall credit history.
Payment history and balances are particularly important account-management considerations. The flyer itself advises cardholders to keep balances low and pay all bills on time every month.
See How PREMIER Bankcard® Reports to Credit Bureaus for a closer look at how monthly reporting works.
How Can the Card Be Used to Build Credit?
The credit-building mechanism is straightforward: if an account is opened and the issuer reports account activity, the account can become part of your credit history. The way you manage the account then matters.
The current PREMIER offer specifically recommends keeping balances low and paying bills on time every month. Those are account-management behaviors that can help avoid negative payment information and keep balances manageable.
You do not need to carry a balance or pay interest simply to build credit. Using a credit card responsibly means borrowing only what you can repay and making required payments on time.
For a broader explanation, see How PREMIER Bankcard® Can Help Build Credit and Responsible Credit Card Use Strategies.
What Happens After 12 Months?
The flyer contains an important statement that is easy to overlook: "Credit Limit Increase Eligible after 12 months of consistent responsible account management."
This does not say that every cardholder automatically receives an increase after 12 months. It says the account becomes eligible for consideration after the stated period if the account has been managed consistently and responsibly.
The mailer does not specify a guaranteed increase amount or state that every eligible account will receive one. The actual terms and account status determine what happens when an increase is considered.
For more information, see How PREMIER Bankcard® Credit Limit Increases Work.
What Other Features Does the Flyer Highlight?
The offer highlights several account-management and card features in addition to the credit limit and credit-reporting language.
| Feature | What the Offer Says |
|---|---|
| 24/7 account access | Access through the mobile app and full-service website |
| Identity theft resolution | Complimentary Mastercard Identity Theft Resolution Services, subject to Mastercard guidelines |
| Credit limit increases | Eligible after 12 months of consistent responsible account management |
| Overlimit fees | No overlimit fees stated in the offer |
| Penalty APR | No penalty APR stated in the offer |
These features are different from the credit-building mechanism itself. For example, 24/7 account access can make it easier to monitor an account, but simply having access to an app does not build credit. Likewise, identity-theft assistance is an account benefit rather than a credit-building activity.
More information is available in 24/7 Account Access & Digital Tools, Mastercard® Identity Theft Resolution Benefits, and Does PREMIER Bankcard® Charge Overlimit Fees?.
What Is the APR?
The mailer excerpt provides the fee ranges and other account terms but directs the recipient to the Terms and Conditions insert for rates, fees, and important disclosures. The exact APR should therefore be taken from the Terms and Conditions accompanying the specific offer rather than assumed from the headline flyer.
APR is also separate from the Program Fee, Annual Fee, and Monthly Fee. Fees can apply regardless of whether you carry a balance, while APR determines the interest cost associated with balances subject to interest under the account's terms.
See Understanding Your PREMIER Bankcard® APR for a detailed explanation.
What If You Do Not Want the Offer?
You are not required to respond to a prescreened credit-card offer. The current mailer also provides an opt-out number for consumers who want to stop receiving prescreened offers from this and other companies.
The number printed on the offer is 1-888-567-8688. The mailer directs consumers to the Prescreen & Opt-Out Notice in the Terms and Conditions insert for additional information.
If you do not want the card, simply receiving the mailer does not require you to activate or apply for the account.
Important Details Printed in the Current Offer
The following details come directly from the offer described on this page and are worth checking against your own mailer.
- Response deadline: October 12, 2026.
- Website: www.MyCreditPremier.com.
- Phone: 800-603-8585.
- Advertised credit limit: Up to $700.
- Approved credit-limit range: $300 to $700.
- Initial available-credit range: $225 to $613.
- Program Fee: $0 to $95.
- Annual Fee: $25 to $99.
- Monthly Fee: $0 to $10.
- Minimum income requirement: $10,000.
- Monthly reporting: The offer states that PREMIER reports to Consumer Reporting Agencies.
- Credit-limit increase language: Eligible after 12 months of consistent responsible account management.
- Overlimit fees: The offer states there are none.
- Penalty APR: The offer states there is none.
- Identity theft benefit: Complimentary Mastercard Identity Theft Resolution Services, subject to Mastercard guidelines.
- Availability restrictions: The offer is not available to residents of New York or Wisconsin.
- Military Lending Act restriction: The offer is not available to active duty military personnel and covered dependents as defined in the offer.
Check your own paperwork: This page explains the specific offer supplied for this guide. Credit-card offers can change, so the Terms and Conditions and disclosures that accompany your own mailer control the actual account terms.
Questions to Answer Before You Apply
The word PRE-APPROVED can make the large headline on a mailer easy to focus on while the more important financial details receive less attention. Before responding, work through the following questions.
- What credit limit am I actually likely to receive within the stated $300 to $700 range?
- What Program Fee applies to my offer?
- What Annual Fee applies to my assigned credit limit?
- What Monthly Fee applies?
- How much initial available credit will I have after applicable fees?
- What APR and other rates appear in the Terms and Conditions?
- Can I comfortably manage the account without carrying a balance I cannot repay?
- Does the card's fee structure fit my budget?
- Do I meet the income and other eligibility requirements?
- Am I comfortable with the credit limit and available-credit structure?
- Do I understand how the account will be reported?
- Have I reviewed the disclosures accompanying the mailer?
PREMIER Pre-Approved Offer vs. Applying for Another Card
Receiving a PREMIER offer does not mean it is the only credit-building option available. A prescreened offer is simply a specific solicitation based on an initial review of credit information.
Other cards may use different structures. Some are secured and require a deposit. Some are unsecured. Some offer rewards. Fees, credit limits, reporting practices, and eligibility requirements can vary significantly from one card to another.
If you are comparing alternatives, see PREMIER Bankcard® vs. Secured Credit Cards and PREMIER Bankcard® vs. Other Credit-Building Cards.
The Short Version
The current PREMIER Bankcard® mailer is a prescreened invitation to apply, not a guarantee that an account is already approved. If approved, the stated credit limit is $300 to $700, while initial available credit is listed at $225 to $613 after applicable fees. The offer lists a Program Fee of $0 to $95, an Annual Fee of $25 to $99, and a Monthly Fee of $0 to $10.
The offer states that PREMIER reports monthly to Consumer Reporting Agencies, provides 24/7 account access, includes complimentary Mastercard Identity Theft Resolution Services subject to Mastercard guidelines, and makes the account eligible for consideration for a credit-limit increase after 12 months of consistent responsible account management.
The most important step is to read the complete Terms and Conditions that came with your offer. The large PRE-APPROVED headline tells you that you were selected for the solicitation. The disclosures tell you what the account actually costs and how it works.
Key Takeaways
- PRE-APPROVED means you met initial criteria for the solicitation. It does not mean an account is already open.
- The current offer states that your credit history met PREMIER's basic approval standards.
- Final approval and the assigned credit limit are determined when the application is evaluated.
- The disclosed credit-limit range is $300 to $700, with an advertised maximum of $700.
- Initial available credit is listed at $225 to $613 because applicable fees reduce the amount initially available.
- The current offer lists a Program Fee of $0 to $95, an Annual Fee of $25 to $99, and a Monthly Fee of $0 to $10.
- The Annual Fee and Monthly Fee may change in the second year.
- The current offer states that PREMIER reports monthly to Consumer Reporting Agencies.
- The flyer says the account becomes eligible for a credit-limit increase after 12 months of consistent responsible account management, but it does not guarantee an increase.
- The offer deadline shown on the current mailer is October 12, 2026.
- The complete Terms and Conditions accompanying the mailer should be reviewed before applying.
PREMIER Bankcard® Mastercard® Navigation
- Why You Received This PRE-APPROVED Offer
- How PRE-APPROVED PREMIER Bankcard® Offers Work
- PRE-APPROVED vs. Unsolicited Credit Card Offers
- Pre-Approval vs. Full Credit Card Approval
- Understanding Your PRE-APPROVED Credit Limit
- How Credit Limits Are Evaluated
- How PREMIER Bankcard® Credit Limit Increases Work
- PREMIER Bankcard® Fees and Costs Explained
- Understanding Your PREMIER Bankcard® APR
- How PREMIER Bankcard® Reports to Credit Bureaus
- Responsible Credit Card Use Strategies
- How to Avoid Unnecessary Credit Card Fees
- Does PREMIER Bankcard® Charge Overlimit Fees?
- Mastercard® Identity Theft Resolution Benefits
- 24/7 Account Access & Digital Tools
- How to Respond to Your PRE-APPROVED Offer
- How Credit Card Prescreening Works
- How PREMIER Bankcard® Can Help Build Credit
- PREMIER Bankcard® vs. Secured Credit Cards
- PREMIER Bankcard® vs. Other Credit-Building Cards
- When PREMIER Makes Sense vs. Alternatives
- Credit Cards Master Hub